
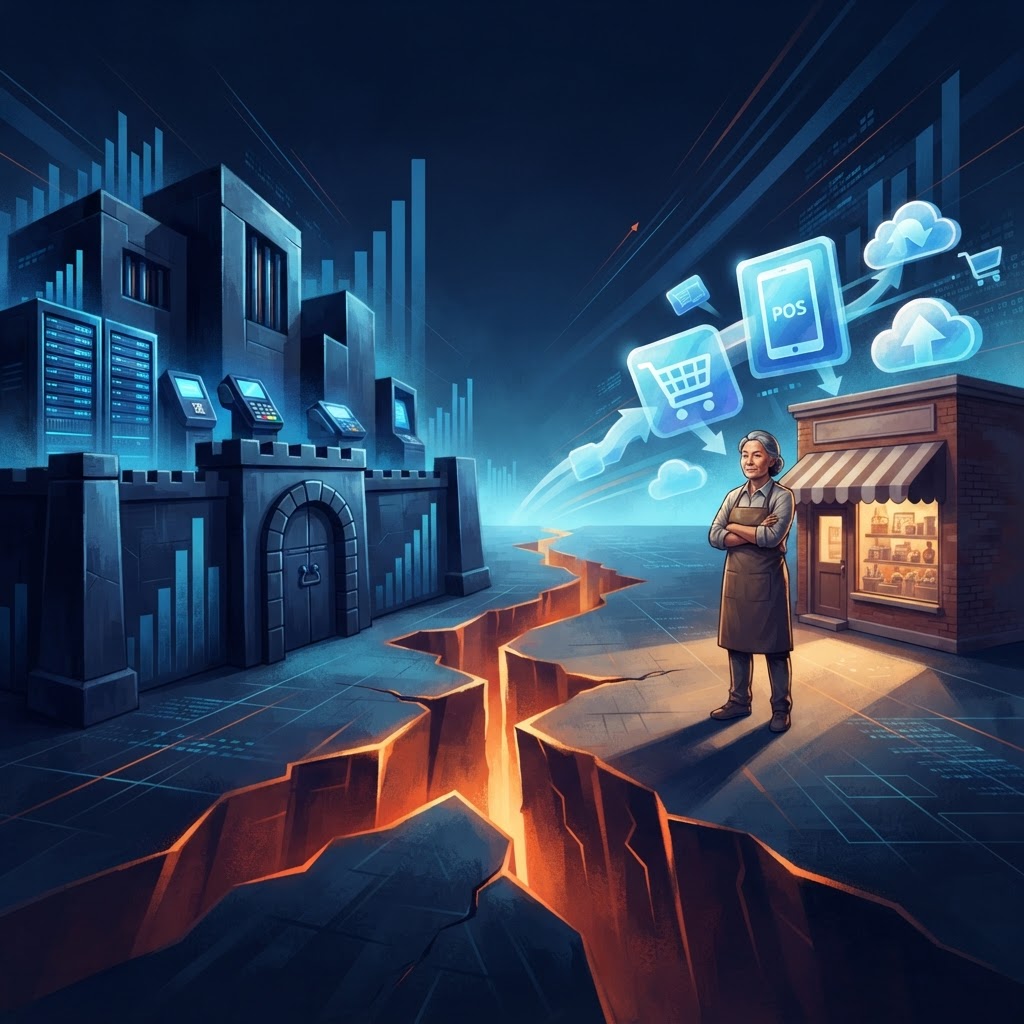
The Payments Industry Is Consolidating. Merchants Aren't Switching.
The next battle in payments is not about a cheaper rate. It is about who can unlock meaningful merchant value without breaking what already works.
That distinction decides which agents win the next five years and which become a replaceable distribution channel inside someone else's ecosystem.
A collision, not a slowdown
Processors are expanding into software. ISVs are embedding payments. Banks, gateways, and fintech platforms are all competing for control of merchant relationships, distribution, and recurring revenue.
At the same time, established retailers have spent years integrating ERP, POS, inventory, accounting, and payment infrastructure. For them, replacing a working payment provider is rarely a pricing decision.
Payments has a distribution problem disguised as a pricing problem. The industry keeps launching products while merchants keep asking whether the benefit justifies the disruption.
For independent agents, that creates an uncomfortable reality: a genuinely strong payment proposal can still be irrelevant if the merchant's software environment cannot support it economically.
Why established retailers keep saying no
Picture a retailer processing $1 million monthly on an established ERP with integrated POS, inventory, accounting, and payments. Checkout works. Transactions settle. Refunds process. Employees know the system.
An ISO arrives with a lower rate.
The CFO is interested. Then IT has to validate compatibility. Operations has to protect checkout reliability. Accounting has to understand reconciliation changes. The ERP provider may need to certify a new gateway.
A processing proposal just became an operational project.
The merchant is not rejecting the savings. The merchant is rejecting an incomplete business case.
Some environments do support multiple gateways and processors. Others carry hard technical and contractual restrictions. The trusted adviser knows the difference before recommending change. Without that, waiting is the rational choice.
The real threat is losing access to the merchant
Agents have always competed on relationships, expertise, and terms. Those strengths still matter.
But software increasingly decides payment selection before the agent is in the room. A retailer chooses an ERP. A dealership selects management software. A service business adopts a vertical platform. Each decision can determine which processors, gateways, devices, and integrations are even possible.
An ISO can have the better proposal and no viable path into the workflow.
That is the structural threat: becoming a replaceable distribution channel inside an ecosystem controlled by someone else. As processors, ISVs, gateways, and fintech platforms converge, control of the merchant relationship decides the long-term economics. Who owns the contract, the pricing, the customer data, the recurring revenue, and the accountability when something breaks.
The industry adds products. Merchants ask for outcomes.
ACH, embedded payments, modern POS, digital wallets, stablecoins, and receivables automation keep expanding what is possible. Availability is not demand.
A retailer with functioning checkout may have zero interest in new terminals, yet an urgent need to cut reconciliation cost, automate receivables, open a new location, or fix its payment mix. A distributor may care far more about collecting large invoices efficiently than adding another checkout option.
The opportunity is not defined by what a provider wants to sell. It is defined by what the merchant has a compelling reason to improve: where money is leaking, where cash is delayed, which manual work is eating staff time, what is missing, and which business event would make change worth it.
Would $500,000 in annual improvement get your attention?
Back to that retailer at $1 million per month, $12 million a year.
A conventional proposal might offer a 20-basis-point reduction: about $24,000 a year if applied to all volume. Worth reviewing. Not worth dismantling a complex ERP integration.
Now widen the assessment. Suppose $100,000 of monthly card-paid invoices moved from an illustrative 2.9% card rate to 0.8% ACH. That is another $25,200 a year before other costs. Accounting for overlap, the combined illustrative gross opportunity lands near $46,800 annually.
A credible adviser then keeps looking: reconciliation labor, duplicated software, receivables delays, payment exceptions, integration maintenance. Could the total reach $100,000, $250,000, or $500,000 a year? Possibly, in a business with large, demonstrable inefficiencies. Those are questions for an assessment, not promises in a proposal.
A $500,000 improvement would be more than 4% of that retailer's annual payment volume. It requires a substantial, independently validated case.
The important change is the conversation itself. Instead of asking a merchant to switch for a marginal rate gain, ask whether its broader payment and financial operations contain a material opportunity worth investigating. The right number is not the biggest savings claim. It is the net value that survives after the full cost and risk of change.
When merchants actually do change
Established retailers do switch. Willingness rises when a business event exposes a limitation:
- An ERP upgrade creates a reason to reconsider integrations.
- A new location needs capability the incumbent cannot deliver efficiently.
- A contract renewal exposes unfavorable terms.
- An acquisition surfaces fragmented systems.
- Persistent reconciliation problems, costly manual collections, or weak support make the cost of staying visible.
These are buying triggers. The next generation of successful ISOs will not simply prospect for large volume. They will identify merchants whose circumstances create a compelling reason to act — which requires vertical expertise, software relationships, financial analysis, and the ability to engage IT, finance, and operations together.
Five changes the channel must make
- Lead with business discovery, not rate comparisons. Establish the financial or operational problem before proposing anything.
- Qualify software compatibility early. Understand the ERP, POS, gateway, and integration constraints before making promises.
- Build partnerships around outcomes. Align implementation, support, commercial terms, and responsibilities across every provider involved.
- Protect partner economics and merchant relationships. Make ownership, residuals, pricing, data access, and expansion rights explicit.
- Measure total merchant value. Weigh implementation cost, operating efficiency, payment mix, and retention alongside processing fees.
These are not tweaks to a sales pitch. They are a different operating model for independent distribution.
Why TrustPay.us
TrustPay.us exists to help agents, ISVs, and referral partners compete in this environment without assembling a separate vendor ecosystem for every merchant need. We connect card processing, ACH, modern POS, hardware, online payments, receivables automation, crypto acceptance, and payment-cost optimization.
But product breadth is not the starting point.
The starting point is understanding what the merchant already has, what is working, and where a real improvement may exist. Sometimes that means replacing outdated technology. Sometimes it means adding ACH or automation alongside existing systems. Sometimes it means improving the economics of the current arrangement. And sometimes the right recommendation is to leave the environment alone until there is a compelling business reason to act.
Keep what works. Fix what doesn't. Add what creates value.
For partners, the conversation is practical: winning merchants with stronger business cases, finding additional revenue, improving retention, coordinating implementation, and setting transparent commercial responsibilities. Start with the TrustPay.us ISO partner program or the referral program, and use the fee audit to build the case on facts.
Executive outlook: the divide ahead
Five forces will reshape payment distribution through 2027.
Software-led distribution will keep gaining influence over which payment provider a merchant even considers. Consolidation will pressure independent partner economics and customer ownership. Retailers will demand more complete financial justification before accepting operational disruption. ACH, alternative methods, and automation will create opportunity beyond cards, but only where they solve measurable problems. And accountability across technology, implementation, and support will become the clearest differentiator.
One conclusion follows.
The payments industry's greatest threat may be its own sales model. We keep approaching established merchants with replacement proposals when their priority is continuity. We keep adding products when the real obstacle is integration. We keep defending residuals while software platforms quietly take control of distribution.
The independent ISO is not obsolete. But the ISO that cannot navigate merchant technology, operational risk, and financial decision-making will face mounting pressure. The next generation of successful partners will know when to replace a system, when to integrate with it, and when to leave it alone.
For merchants, the question is not whether a better product exists. It is whether the business can achieve a meaningful, measurable improvement without putting what already works at risk.
For agents and ISVs, the opportunity is to become the partner who can answer that question — and for a retailer processing $12 million a year, even a fraction of a demonstrated $500,000 opportunity deserves a serious conversation.
One connection can change everything.
Contact TrustPay.us to talk through your merchants, your territory, and what a stronger business case looks like.
Industry methodology and references
Industry methodology: numerical scenarios are illustrative unless a named source and method are supplied; they are not measured TrustPay customer outcomes. Calculate card cost using the actual invoice value and quoted rate, then include transaction, platform, return, conversion and settlement charges for alternatives. ACH requires authorization and can be returned. Crypto finality is not a guarantee against fraud, refunds or payout delays. Cash discount, dual pricing and surcharging are distinct programs subject to applicable rules. Implementation and savings depend on the business, customer adoption and actual contract.
Which payment workflow fits the industry problem?
Compare the full cost of cards, suitable ACH payments and optional crypto acceptance. Start with the actual fee schedule, customer payment preferences and settlement needs.
Get Your Free Quote →